That passphrase isn't right. Check your invitation email, or contact harry.massey@e4l.com.
Confidential. For accredited investors only. Securities offered under Rule 506(c) of Regulation D; accredited status is verified before any subscription is accepted. Site access is granted by E4L, Inc.
Every answer links to the page that proves it — the model, the science, the deal, the documents. New here? Start with the overview.
We believe physics is becoming the defining paradigm in health this decade — and E4L is one of the first companies building products from a physics-first view of the body. The chain is simple: physics controls chemistry, and chemistry controls biology. Medicine has spent a century mastering the chemistry; E4L works one layer down — on the fields, voltage and information the body actually runs on. Your DNA is identical alive or dead; the difference is energy. This is additive to medicine, never against it.
Why now: chemistry's productivity is collapsing (drug-discovery cost roughly doubles every nine years — "Eroom's Law"), while the physics curve is only beginning. Treat the body as an operating system — work at the information layer — and health starts to behave like software, with software-like margins. Wearables are a $92.9B market that only measures; nothing detects and corrects your energy at home, every day. That is the category E4L was formed to own — with a two-decade head start it bought, not one it has to build.
E4L, Inc. is a new company (incorporated 2026, headquartered in Salt Lake City) that acquired the products, IP and data of XPO Health / NES Health, the UK bioenergetics pioneer. FIELD is the AI platform at the centre — and E4L owns it outright, through the acquired NES Health LLC subsidiary. The GEM wearable, the miHealth handheld, infoceutical consumables (drinkable drops of energized structured water — the same input the published cell study tested), the consumer app, ~650 acquired practitioners and the Beyond Medicine streaming audience are the ecosystem that feeds it. The core diagnostic platform and the products are owned outright.
One science, many carriers — the same information delivered through water, light + field, and sound. Detect → Correct → Protect.
Wearables: $92.9B (2025), projected $230.0B by 2033 — Grand View Research, Wearable Technology Market.
The full thesis — The Physics-First Healthcare Transition How the science underwrites it — The Proof
The GEM — the wearable that goes beyond biometrics: it detects and corrects.
Proprietary bioenergetic scans — FIELD's training data.
Acquired dataset · 26 yearsYears of products, IP and data, acquired at formation.
Asset acquisition, 2026A founder who lived the mission, and operators hired to scale it. Harry Massey spent seven years bedridden with severe fatigue; conventional approaches failed him, so he spent 20+ years inventing what he wished had existed — and tested everything on himself first. Three wounds became three inventions: a post-viral collapse (Information → Infoceuticals), a 60-ft climbing fall and spinal fracture (Voltage → miHealth), and emotional exhaustion (Resistance → the GEM).
Board of directors: Harry Massey (Chairman & CEO) and Susan Kichuk, with one board seat currently open.
Advisors: Prof. Hemal Patel, PhD (UCSD — scientific advisor) · Dr. Zulia Frost (clinical practice).
From bedridden years to the 2026 return climb — filmed for Beyond Medicine.
Harry's recovery is his personal experience, not a product claim. His filmed, on-the-record story is the category's marketing engine. On terms: Harry has contributed an estimated $15–20M of real capital over 20 years — context, not the value of his holding company's stock, which took only $3.2M of junior Class B Preferred (its cost); his upside sits in ordinary Founder Common alongside every common holder, with a single 1× non-participating preference for cash invested (your money senior). Detail on the Deal page.
A running engine, bought whole. E4L, Inc. is a new company (2026, Salt Lake City) that acquired the products, IP, data and customer base of XPO Health / NES Health — assets Harry spent two decades building, and that would take a competitor two decades and tens of millions to replicate. The acquired base gives the company revenue from day one (~650 practitioners, infoceutical wholesale running at ≈$3.5M/yr at close). Everything new on top — the GEM, the consumer app, the new miHealth, FIELD and the film — has zero revenue history, and the forecast says so.
New company. New team. New model.
Acquired assets — not inherited claims.
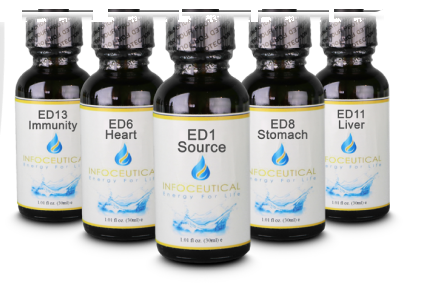
The Infoceutical library — one of the acquired asset families.
Historical customers in the acquired file.
Asset acquisition, 2026Active practitioners transferring with the purchase.
Asset acquisition, 2026Three levels of evidence, all pointing the same way — molecule, cell, and human. The credibility strategy is "go via the universities": lead with the published, peer-reviewed work and label the pilot honestly.
Blinded living-cell study: ≈37% less oxidative stress in treated cells; 1,139 genes showed altered expression (717 up / 422 down).
"A cell has no mind. It can't believe. There's no placebo to hide behind." — Prof. Hemal Patel, PhD, UCSD; scientific advisor to E4L
A cellular study — a biological effect on energy and oxidative-stress markers, not a clinical outcome in people.
≈39% lower self-reported anxiety scores (p=0.007) · ≈52% lower self-reported fatigue scores.
Observational pilot, no control group — directional, not definitive. A controlled study is in the funded R&D plan.
1M+ bioenergetic scans · 26 years of proprietary data — what makes the FIELD platform trainable and defensible.
These are wellbeing measures — stress markers, self-reported energy and mood — not disease endpoints.
UC San Diego School of Medicine — where researchers conducted the EXPLORE cell study.
Consumers — a subscription-first wellness system: free 30-day app trial → Member $10/mo → GEM plan $30/mo (requires the $397 GEM) → Guided $90/mo (three Infoceuticals shipped monthly on a three-month commitment, Member included); singles at $33 a bottle, and a personal re-scan every 30 days that refreshes the three — a built-in reorder cycle.
Practitioners — ~650 acquired, each one a storefront: a $1,000-deposit 60-day trial converts to the miHealth ($5,000) and the FIELD system on rent-to-own ($3,997 down + $397/month × 5 years, or $20,000 upfront), then wholesale margin recurs on everything they retail ($19 wholesale → $33–38 retail infoceuticals).
Top of funnel we own: Beyond Medicine streams August 2026 and routes its audience into the app trial and Cell Driver+ funnels; the practitioner locator hands consumers who want more to the acquired network; a Salt Lake City inside-sales team is hired by Sept 2026.
Sequence: film (Aug) → beta app (Aug) → revenue on (Sept) → practitioner re-activation (Q4).
The funnel assumptions, in the model — The Numbers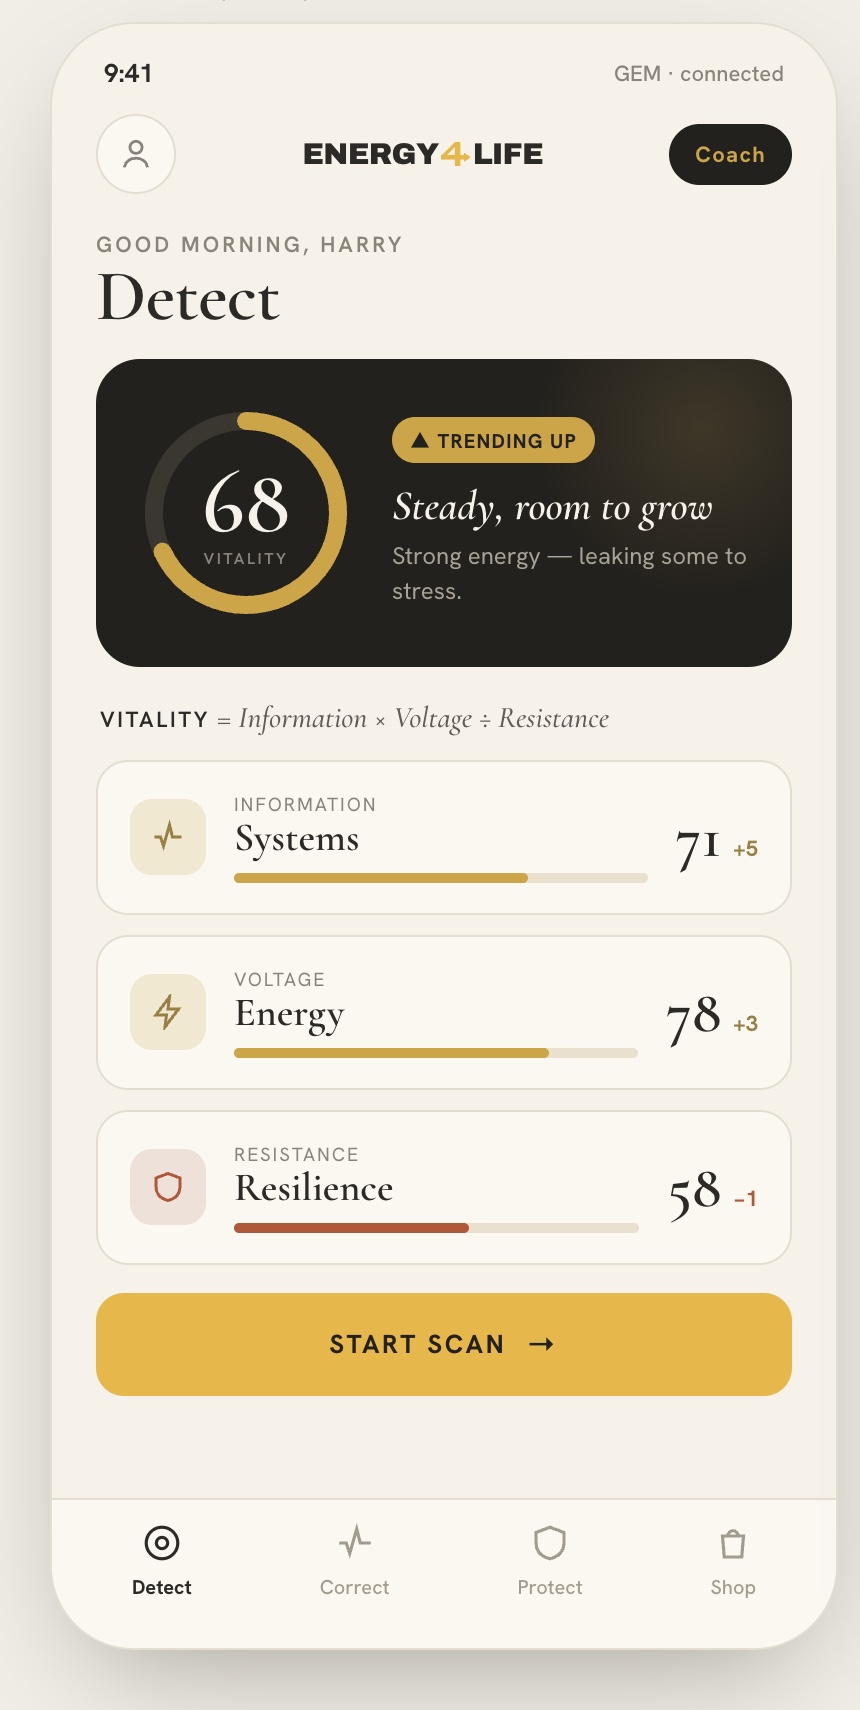
The consumer front door: a free 30-second scan, a Vitality Score, one next step.
The GEM app is the gateway, not the destination (free 30-day trial → Member $10 → $30 GEM plan / $90 Guided) — a low-cost front door that turns consumers into buyers of the GEM and infoceuticals, into clients, and moves some up into coaches and practitioners. The revenue engine is the products and the practitioner channel.
Consumer subscription · the funnelSoftware LTV signal per practitioner, from the acquired platform's data.
Acquired-platform data · assumption inputHardware opens the door. Recurring revenue owns the house. Six revenue lines — consumer: app subscriptions, GEM hardware, infoceutical consumables; practitioner: miHealth devices, FIELD SaaS (rent-to-own), wholesale consumables. Software-like margins on physical products, because the value is in the information, not the materials.
Every device sale seeds at least one recurring line — app subs behind the GEM; SaaS and wholesale behind the miHealth. Blended gross margin: 80–85%. Consumables and subscriptions compound; devices are the acquisition event, not the business.
Drivers & unit economics — The Numbers| Product | COGS | Price | Gross margin |
|---|---|---|---|
| GEM wearable | $85 | $397 | ~79% |
| Infoceutical | $1.50 | $33–38 | ~95% |
| miHealth | $200 | $5,000 | 96% |
miHealth COGS confirmed at $200 (Harry, 2026-07-09).
Four of the six lines recur; the two device lines are the acquisition event, not the business.
Revenue starts September 2026 with $2.7M (Q4 2026, the first quarter of revenue) — a partial period, not a full year — then reaches $16.0M in FY2027, the first full year, and scales to $134.7M by FY2031. Built bottoms-up on the confirmed drivers across all six lines.
| Q4 2026 | FY27 | FY28 | FY29 | FY30 | FY31 | |
|---|---|---|---|---|---|---|
| Revenue | $2.7M | $16.0M | $34.3M | $57.9M | $94.0M | $134.7M |
+$1.7M FY27 → +$39M FY31 (29% margin), after a disciplined R&D reinvestment. Gross margin 80–85% throughout, blended, per confirmed model drivers.
Minimum cash across the whole plan, funded by one $5M SAFE — building to $67M by end-2031 after tax, no further raise assumed.
By 2031, with 8%/yr churn modeled. Practitioner wholesale ~$450/month per active practitioner today, rebuilding to $600 (historical peak $720), plus $397/month rent-to-own while renting. The bottoms-up model by all six lines is on the Numbers page.
Projections are illustrative, based on management assumptions; actual results will differ. Model v2.6, prepared July 2026.
Everything on the Numbers page is the conservative floor — a products business we can defend line by line. It excludes the reason E4L could become something far larger.
E4L's rarest asset is a capability no one else has assembled: mapping the body's physics and inventing products from it, and — as the FIELD dataset grows — mapping how specific fields change cells. That mapping is licensable: pharma, device and longevity companies would pay to know which field does what. We have modeled none of that licensing revenue.
Three curves are converging — AI trained on biological data, quantum-grade sensors, and the recognition that physics governs biology. A first mover holding the data and the patents at the interface between intelligence and the cell has a real shot at defining the category — a potentially trillion-dollar outcome. That is the honest bull case: a moonshot, explicitly NOT in our forecast — our numbers are the floor beneath it.
The full thesis — The Physics-First Healthcare TransitionLicensing revenue in the forecast — the field-mapping upside is excluded until deals are signed and modelable.
Model v2.6 · deliberately conservativeFirst mover mapping the body's physics and inventing products from it.
Category-defining capabilityThe floor is a real business. The ceiling is a new category.
Raising $5M on a YC-style SAFE · $73M post-money cap + 15% discount, converting at the lower of the two · accredited investors only (Reg D 506(c)). Deliberately simple. The cap is a negotiated term of this round. With the discount, your effective entry likely sits below the cap (Series A intended within ~18 months; if a sale comes first, the same lower-of terms apply to the sale price). And the cap prices the harshest reading of our own plan: discount the FY31 numbers (~$39M EBITDA at a conservative 10×) back at 30–40%/yr and today's implied value is ≈$73–105M — while the lower-of terms guarantee you convert at least 15% below the Series A price — an ~18%+ instant mark-up. E4L is a new company that starts with acquired products, ~650 practitioners and recurring revenue from day one — not a concept waiting for its first customer. Your SAFE converts into Class A Preferred — a 1× non-participating preference that is senior. No escrow, no tranching; the assets are already in the company.
The preference is deliberately clean: a single 1× non-participating preference for cash actually invested — your money (Class A) senior, the founder's own $3.2M and one early investor's ~$1.6M (Class B) junior, no participation, multiples or stacking; on a big exit everyone converts to common and all upside is shared, so nobody double-dips. What your money buys, concretely: your percentage is set at the Series A — you convert at the lower of the $73M cap or 15% below the round price, so the full $5M is at least ~6.8% of the company, ~8.1% at a $73M round, and ~10% at a ≈$59M round. On alignment: Harry has contributed an estimated $15–20M of real capital over 20 years — that's context, not the value of his holding company's stock, which took only $3.2M of junior Class B Preferred (its cost). His own upside sits in ordinary Founder Common alongside every common holder (board control via his majority ownership and director-designation rights, not economic preference). SAFEs carry no voting rights until conversion (standard). See the cap structure & waterfall; detail on the Deal page.
Use of funds (growth-weighted): $1.0M GEM inventory · $1.0M+ R&D (FIELD/AI + controlled clinical studies) · $1.5M consumer growth (film funnels, the app, infoceutical offers) · $1.0M+ operations & team (Salt Lake City) — the balance held as cash cushion.
Milestones to the priced round: film streams + beta app (Aug 26) → revenue on + sales team (Sep 26) → FY27 revenue ≈$16M → FIELD commercial launch → priced round from strength.
SAFE, cap table & investor FAQ — The DealPost-money cap plus a 15% discount; you convert at the lower of the two.
Cap + discount SAFE (YC style)Intended window for the priced Series A that converts your SAFE. If a sale comes first, the same lower-of terms apply to the sale price.
Expectation, not a commitmentThe balance is held as cash cushion.
Milestones to the priced roundFull transparency is a feature of this raise, not a footnote. Every investor receives and acknowledges a complete Disclosure Memorandum covering the restructuring and asset acquisition — read it in full; acknowledgment is required before closing.
Sophisticated investors reward honesty. The caveats live on the same page as the claims.
Five steps, all standard, all documented on the closing page:
Accredited-investor questionnaire (download on the Close page), plus verification of accredited status — usually a short letter from your CPA, attorney or registered adviser.
The SAFE + Disclosure Memorandum acknowledgment — e-sign or PDF.
From E4L, Inc.
Verify by phone with Harry before wiring — we will never change wire details by email. Full instructions are sent to you individually after the countersigned SAFE.
Form D, update cadence, and your documents.
All follow-up runs through harry.massey@e4l.com — the @e4l.com domain only.
Read the overview, open the model, review the deal — then let's talk. Beyond Medicine streams August 2026.
This page contains illustrative projections and wellness (structure/function) product descriptions only; E4L products are not intended to diagnose, treat, cure, or prevent any disease.